PhilHealth and Pag-IBIG contribution for kasambahay 2026
At a ₱7,800 salary, remit ₱500 to PhilHealth and ₱312 to Pag-IBIG monthly. See employer and worker shares, registration forms and payment checks.

Charles writes for Helpers.

Direct answer: At the NCR kasambahay wage floor of ₱7,800, PhilHealth costs ₱500 a month because its income floor is ₱10,000. The employer and worker each pay ₱250. Pag-IBIG is 2 percent from each side on wages over ₱1,500, capped at a ₱10,000 fund salary, so each share is ₱156 at ₱7,800. Register the hire with unified kasambahay forms.
| Contribution | 2026 rate | Employer share | Kasambahay share | Monthly amount at ₱7,800 wage |
|---|---|---|---|---|
| PhilHealth | 5% of monthly basic salary, with a ₱10,000 floor and ₱100,000 ceiling | 50% of premium | 50% of premium at wages of ₱5,000 or more | ₱500 total, ₱250 each |
| Pag-IBIG | 2% each for wages over ₱1,500, on a maximum fund salary of ₱10,000 | 2% | 2% | ₱156 each |
The ₱7,800 example is the NCR floor in the 2026 kasambahay minimum-wage guide. Under Section 30 of Republic Act 10361, the employer pays the whole premium when monthly pay is below ₱5,000. At ₱5,000 or more, the kasambahay pays a proportionate share.
Most families sort out SSS and stop there. It has the biggest number, the most familiar name, and a contribution table everyone has seen. PhilHealth and Pag-IBIG then sit unpaid for years, usually because nobody told the household they were part of the same obligation.
They are, and the same sentence of the same law creates all three. The PhilHealth half is also easier than the SSS half, because there is only one figure to learn. This guide says "she" because most kasambahay are women, and every rule applies the same way to men. SSS has its own SSS contribution guide, so nothing here repeats it.
One law, three agencies, one month of service
Section 30 of Republic Act 10361, the Batas Kasambahay, is short and it covers everything: a domestic worker who has rendered at least one month of service is covered by SSS, PhilHealth and Pag-IBIG, and is entitled to all the benefits those laws provide. The same section puts the premiums on the employer, then adds one condition. A kasambahay earning ₱5,000 a month or more pays the proportionate share.
Section 4 of the same act tells you who counts: general househelp, nursemaid or yaya, cook, gardener, laundry person. If she works in your home in an employment relationship, she is covered.
Watch out for two different ₱5,000 figures that get mixed up constantly. One is the RA 10361 wage line above which a kasambahay starts paying her own share. The other is the old Pag-IBIG maximum fund salary, which was ₱5,000 until February 2024. They are unrelated numbers that happen to match, and confusing them is how households end up deducting the wrong amount.
Use the salary agreed in the contract for the contribution calculation, and check it against the current regional wage table. Contribution thresholds and regional wage floors are different rules. A correct contribution calculation does not make a below-minimum salary lawful.
PhilHealth 2026: five percent, and a floor that decides everything
PhilHealth Advisory No. 2025-0002 states the current setting plainly. The premium rate effective the applicable period of January 2025 remains at 5.0 percent, with an income floor of ₱10,000 and an income ceiling of ₱100,000. PhilHealth Advisory No. 2026-0042, issued this year, repeats that direct contributors pay 5.0 percent of monthly income effective January 2025 and that the minimum monthly premium is ₱500.
The floor is the part that matters for a household. PhilHealth Circular No. 2020-0005 says that for those whose basic monthly salary is below the income floor, the premium is computed on the income floor. Your kasambahay earns less than ₱10,000. So you do not multiply 5 percent by her salary. You multiply it by ₱10,000, and you get ₱500.
That is the whole computation. It does not change between Metro Manila and Bukidnon, and it does not move when you give her a raise, until the raise takes her past ₱10,000.
The same circular defines what "monthly basic salary" means, and it is narrower than take-home pay. It is the fixed basic rate, excluding sales commission, overtime pay, allowances, thirteenth month pay, bonuses and other gratuity payments. Undertime, tardiness, unpaid leave and absences are excluded from the computation too, so a month with deductions does not lower her premium base.
What you actually deduct, at five salaries
Circular 2020-0005 covers household help twice. Once in general, where the premium of employed members including household help is computed on monthly basic salary and shared equally between employee and employer. Then again in a kasambahay paragraph mirroring RA 10361, where the premium is shouldered solely by the household employer unless she receives ₱5,000 a month or above, in which case she pays her proportionate share. Put the two together and the split at any legal wage is straight down the middle.
| Monthly basic salary | Premium computed on | Total premium | Employer share | Worker share |
|---|---|---|---|---|
| ₱5,500 salary example | ₱10,000 | ₱500 | ₱250 | ₱250 |
| ₱6,500 salary example | ₱10,000 | ₱500 | ₱250 | ₱250 |
| ₱7,800 (Metro Manila) | ₱10,000 | ₱500 | ₱250 | ₱250 |
| ₱12,000 salary example | ₱12,000 | ₱600 | ₱300 | ₱300 |
| ₱4,800 (below every legal floor) | ₱10,000 | ₱500 | ₱500 | ₱0 |
The employer remits the full premium, including the amount deducted from the worker. At a ₱7,800 salary, remit ₱500 to PhilHealth, not just your ₱250 share. A payslip deduction alone does not show that the agency received the payment. Keep the remittance receipt and check the posted contribution.
The last row is a trap, not an option. If you are paying ₱4,800, PhilHealth is the smaller of your problems and the wage is the thing to fix first. Use the salary calculator to sanity-check the number before you argue about premiums.
The fourth row carries the only good news here. Pushing her past ₱10,000 is the first raise that costs you anything extra in PhilHealth. Every wage below that is the same ₱250.
Registering: one form, three agencies
You need employer numbers before you can remit anything, and the government made this genuinely easy. The SSS household employer page says the household employer submits one copy of a filled-out Household Employer Unified Registration Form, the PPS-HEUR1, at any branch or service office of SSS, PhilHealth or Pag-IBIG. One counter, one form, three ID numbers.
The SSS kasambahay page explains why this exists. The implementing rules of RA 10361 required a unified system of registration, so the three agencies integrated their processes into a single web service. It is a one stop shop. Through it, household employers and house helpers are issued their membership numbers and covered under all three agencies using just one form.
Three forms make up the system:
- PPS-HEUR1, the Household Employer Unified Registration Form. This is you, once, at the start.
- PPS-KUR, the Kasambahay Unified Registration Form. This is for a kasambahay who does not yet have numbers.
- PPS-HEUR2, the Household Employment Unified Report Form. This reports the employment itself.
Bring her details on day one rather than day thirty. If she already has a PhilHealth number and a Pag-IBIG MID number from a previous job, you are only reporting the new employment, not creating new memberships. Ask for the numbers during the interview and write them into the contract alongside the wage. Our kasambahay law guide covers what else belongs in that contract.
Paying PhilHealth every month
PhilHealth's payment and reporting procedures for employers put remittance through the Electronic Premium Remittance System, a web application employers use for both payment and the remittance report. Payment goes through accredited collecting agents nationwide or the e-pay services of participating banks, BPI, Unionbank, DBP and PNB among them.
The deadline runs off the last digit of your PhilHealth Employer Number. A PEN ending in 0 to 4 pays every 11th to 15th day of the month following the applicable period. A PEN ending in 5 to 9 pays every 16th to 20th. Nothing on that page carves out a different schedule for household employers, so read your own PEN and use the window it falls in. Confirm it at your PhilHealth office before the first remittance rather than after a missed one.
Set a recurring calendar reminder on the 11th. A household of one employee has no payroll department to catch a slip, and the interest on arrears is the expensive kind.
What your kasambahay gets for the ₱500
This is the part worth telling her about, because a deduction with no visible benefit feels like a tax.
PhilHealth's benefits page lists inpatient benefits, paid to accredited facilities through All Case Rates, and outpatient benefits covering day surgeries, radiotherapy, hemodialysis and blood transfusion. Z benefits cover catastrophic illness such as cancer treatment, cardiac surgery and organ transplantation. There are packages for tuberculosis, HIV and rabies post-exposure prophylaxis, outpatient mental health services covering screening, follow-up visits and essential medicines, and maternity and newborn care including care for preterm and small newborns.
Then there is Konsulta, the part almost no household uses and everyone should. PhilHealth Circular No. 2024-0013 enhanced the PhilHealth Konsultasyong Sulit at Tama package and makes all Filipinos eligible. A beneficiary registers with an accredited Konsulta Package Provider of their choice using the PhilHealth Konsulta Registration Form. The package covers health screening and primary care consultations, plus select diagnostic services and medicines as assessed by the provider's physician. Telemedicine visits count, and the provider handles referral to higher levels of care.
Help her register with a Konsulta provider near your home, not near her home province. That is a fifteen-minute errand that turns her ₱250 into an actual annual check-up.
Pag-IBIG 2026: the rate and maximum fund salary
The statute is clear. Section 7 of Republic Act 9679, the Home Development Mutual Fund Law of 2009, sets employee contributions at 1 percent for those earning not more than ₱1,500 a month and 2 percent above that, with employers contributing 2 percent of covered employees' monthly compensation. The law originally capped the compensation used in that computation at ₱5,000, and gave the Board of Trustees power to change that maximum.
The Board used it. DBM Circular Letter No. 2024-2, issued 1 February 2024, quotes Pag-IBIG Fund Circular No. 460 of 15 January 2024 and confirms that the maximum fund salary used in computing employee and employer savings was increased from ₱5,000 to ₱10,000 per month. It reprints the rate table too:
| Monthly fund salary | Kasambahay share | Household employer share |
|---|---|---|
| ₱1,500 and below | 1.0% | 2.0% |
| Over ₱1,500 | 2.0% | 2.0% |
The Presidential Communications Office announcement of the same change gives the peso figures: monthly savings for both the employee share and the employer counterpart rose to ₱200 each from ₱100, starting February 2024.
So ₱200 from each side is the ceiling, reached at a ₱10,000 fund salary. Below that, the 2 percent rate applies to actual pay. At the ₱7,800 Metro Manila wage, that is ₱156 from each side. The Pag-IBIG employer registration and remittance circular sets the employer's 2 percent counterpart and the remittance deadlines. The Fund's Circular 460 raised the maximum fund salary to ₱10,000.
The savings are hers, they earn annual dividends, and she receives them on membership maturity or retirement. The Presidential Communications Office release puts a member saving twenty years under the new rates at around ₱174,000, roughly double the old rates. Membership also opens higher multi-purpose and calamity loan amounts and access to Pag-IBIG home loans. Housing loan eligibility depends on a minimum number of monthly savings, so if she is thinking about a home loan, have her ask Pag-IBIG how many she needs and how many she has.
Combined monthly remittance at three salaries
Separate the amount the household funds from the amount it sends to each agency. These examples assume a full month, a salary above the ₱5,000 sharing threshold, and no voluntary Pag-IBIG savings. They cover PhilHealth and Pag-IBIG only. SSS remains a separate payment.
| Monthly salary | Employer PhilHealth | Worker PhilHealth | Employer Pag-IBIG | Worker Pag-IBIG | Total sent to both agencies |
|---|---|---|---|---|---|
| ₱7,800 | ₱250 | ₱250 | ₱156 | ₱156 | ₱812 |
| ₱10,000 | ₱250 | ₱250 | ₱200 | ₱200 | ₱900 |
| ₱12,000 | ₱300 | ₱300 | ₱200 | ₱200 | ₱1,000 |
Source and calculation: PhilHealth Circular 2020-0005 defines the premium floor and equal sharing. Advisory 2026-0042 confirms the 5 percent rate and ₱500 minimum premium. DBM Circular Letter 2024-2 reproduces Pag-IBIG Circular 460's 2 percent shares and ₱10,000 maximum fund salary. Amounts above are computed examples, not survey averages.
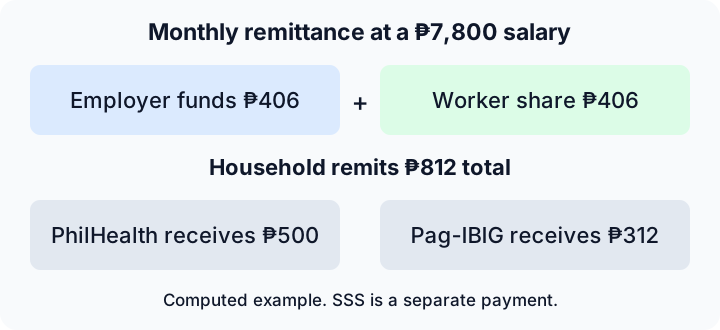
Diagram uses the first row of the table and the same official sources. Of the ₱812 remitted, ₱406 is the household's additional cost and ₱406 comes from the worker's salary. Do not add the worker's share to the household's cost a second time. Use the payslip template to show each deduction and the SSS guide for the remaining agency.
Before you agree on pay, browse helper profiles and write the gross salary and benefits into the offer. Create a family account when you are ready to start hiring.
What happens if you skip it
Here is the part families misread, and it is the single best reason to just pay.
Skipping does not hurt her. Republic Act 11223, the Universal Health Care Act, automatically includes every Filipino citizen in the National Health Insurance Program, and says failure to pay premiums shall not prevent the enjoyment of any Program benefits. Circular 2020-0005 repeats it.
It hurts you. The same circular says direct contributors must pay all missed contributions with interest compounded monthly of at least 3 percent for employers, and that an employer's failure to remit the required contribution and submit the remittance list is an offense under Section 38 of the UHC Act. On top of that, Section 40 of RA 10361 punishes violations of the kasambahay law with a fine of not less than ₱10,000 and not more than ₱40,000. The SSS kasambahay page puts it bluntly: a household employer who fails to report and remit can be sued for violating two laws.
So the debt stays with the household, compounding, while the benefit stays with her. There is no version of this where skipping saves money.
Your monthly checklist
- Compute her PhilHealth premium on the income floor, not her salary, unless she earns over ₱10,000.
- Deduct her half of PhilHealth from the payday nearest the cut-off, not both halves.
- Deduct her Pag-IBIG share at the rate for her fund salary.
- Log in to the Electronic Premium Remittance System and generate the PhilHealth remittance report.
- Pay PhilHealth within your PEN's window, the 11th to 15th or the 16th to 20th of the following month.
- Remit Pag-IBIG through your chosen channel and keep the receipt.
- Issue her payslip showing both deductions by name.
- File the receipts. Three years of records is the habit to build now.
The payslip lines
Section 26 of RA 10361 requires the employer to give the kasambahay a payslip at all times, showing the amount paid in cash and all deductions made. A verbal "I already paid your PhilHealth" is not compliance, and it is the first thing that falls apart in a dispute.
The deduction block on a ₱7,800 Metro Manila payslip carries three named lines: her SSS share, her PhilHealth share of ₱250, and her Pag-IBIG share. Name each one. Never fold them into a single "government deductions" figure, and never deduct your own employer share from her pay, which is not a lawful deduction. Our kasambahay payslip template has the full BK-2 layout with these lines already in place.
If your kasambahay is under eighteen, the contribution rules do not change, but read the age rules in the kasambahay law before anything else. Keep copies of her documents only for as long as registration requires, return every original the same day, and do not circulate her PhilHealth or Pag-IBIG numbers in family group chats.
For the kasambahay: check your own records
You do not have to take anyone's word for it.
Advisory 2026-0042 tells members to verify the posting of their premium contributions through the PhilHealth Member Portal or the eGov PH Super App. Do that every few months. If a month is missing, the record is the evidence, and the obligation to fix it sits with the household, not with you.
For Pag-IBIG, get your own MID number and keep it somewhere your employer cannot lose it. Ask for the remittance receipt each month, the same way you would ask for a payslip. You are entitled to the payslip by law, so asking for it is not a confrontation.
Three things nobody should ever ask of you: a placement fee for the job, your original PhilHealth or Pag-IBIG ID held as security, or a deduction described only as "government" with no breakdown. Any of those is a signal to slow down and get the terms in writing before the next payday.
Frequently Asked Questions
How much is the PhilHealth contribution for a kasambahay in 2026?
PhilHealth Advisory 2025-0002 sets the rate at 5 percent with an income floor of ₱10,000 and a ceiling of ₱100,000, and Advisory 2026-0042 says the 5 percent rate still applies. Every regional kasambahay minimum wage is below the ₱10,000 floor, so the premium is computed on the floor and comes to ₱500 a month. The household employer remits the full ₱500, funding ₱250 and deducting the other ₱250 from her salary.
Who pays the PhilHealth contribution of a kasambahay?
Section 30 of Republic Act 10361 says the employer pays the full SSS, PhilHealth, and Pag-IBIG premiums when monthly pay is below ₱5,000. At ₱5,000 or more, the kasambahay pays a proportionate share. PhilHealth Circular 2020-0005 says household help shares the PhilHealth premium equally with the employer. The 2026 legal wage floors are above ₱5,000 in every region.
How much is the Pag-IBIG contribution for a kasambahay?
For pay over ₱1,500 a month, the rate is 2 percent from the worker and 2 percent from the employer, up to a ₱10,000 maximum fund salary. At the ₱7,800 NCR wage floor, each share is ₱156. At the cap, each share is ₱200.
What happens if I do not remit my kasambahay's PhilHealth and Pag-IBIG?
Your kasambahay keeps her PhilHealth benefits either way, because Republic Act 11223 says failure to pay premiums does not prevent the enjoyment of Program benefits. The household still owes every missed premium with interest compounded monthly at three percent, and an employer who fails to remit commits an offense under Section 38 of the Universal Health Care Act. Republic Act 10361 adds a fine of ₱10,000 to ₱40,000 for violations of the kasambahay law.
How do I register as a household employer with PhilHealth and Pag-IBIG?
File one Household Employer Unified Registration Form, PPS-HEUR1, at any branch or service office of SSS, PhilHealth or Pag-IBIG. The Kasambahay Unified Registration System issues membership numbers for all three agencies from that form. Use the Kasambahay Unified Registration Form, PPS-KUR, for a kasambahay who has no numbers yet, and the Household Employment Unified Report Form, PPS-HEUR2, to report the employment. PhilHealth remittance is due on the 11th to 15th of the following month for employer numbers ending in 0 to 4, or the 16th to 20th for numbers ending in 5 to 9. Pag-IBIG deadlines are 10th to 14th for employers A to D, 15th to 19th for E to L, 20th to 24th for M to Q, and 25th to month-end for R to Z or a numeral.
Budget the ₱500 before you make the offer
The households that get this right do one thing differently. They add the three agencies to the monthly figure before the interview, so the number they quote is the number they can actually sustain. The ones who bolt it on afterwards start looking for reasons the law does not apply to them.
If you are hiring now, start your search on Helpers and put PhilHealth, Pag-IBIG and SSS into the budget on the same line as the wage. Use the payslip template to record the deductions, and retain the separate agency receipts. Open a family account when you are ready to compare candidates. Confirm salary, benefits and remittance responsibilities before the first working day.
Sources checked for this guide
- PhilHealth Circular No. 2020-0005: Premium Contribution Schedule in the National Health Insurance Program Pursuant to R.A. No. 11223 (Revision 1) (Philippine Health Insurance Corporation; accessed 2026-10-25)
- PhilHealth Advisory No. 2025-0002: Premium Contribution for All Direct Contributors for CY 2025 (Philippine Health Insurance Corporation; accessed 2026-09-04)
- PhilHealth Advisory No. 2026-0042: Reimbursement Claims Abroad and Premium Contributions (Philippine Health Insurance Corporation; accessed 2026-10-25)
- Payment and Reporting Procedures: Employer (Philippine Health Insurance Corporation; accessed 2026-09-04)
- PhilHealth Benefits (Philippine Health Insurance Corporation; accessed 2026-09-04)
- PhilHealth Circular No. 2024-0013: Enhancement of the PhilHealth Konsulta Benefit Package (Philippine Health Insurance Corporation; accessed 2026-09-04)
- Household Employer (Social Security System; accessed 2026-10-25)
- Kasambahay (Social Security System; accessed 2026-09-04)
- DBM Circular Letter No. 2024-2: Adjustment in the Employer (Government) Share in the Premium Contributions to the Home Development Mutual Fund (Pag-IBIG Fund) Effective February 2024 (Department of Budget and Management; accessed 2026-10-25)
- Pag-IBIG members to gain more benefits under new rates starting February 2024 (Presidential Communications Office; accessed 2026-09-04)
- Pag-IBIG Fund Circular No. 460: Increase in the Maximum Fund Salary Effective February 2024 (Home Development Mutual Fund; accessed 2026-10-08)
- Pag-IBIG Fund Circular No. 275: Employer Registration, Contribution, and Remittance (Home Development Mutual Fund; accessed 2026-10-08)
- Current Monthly Minimum Wage for Domestic Workers as of July 9, 2026 (National Wages and Productivity Commission; accessed 2026-09-04)
- Republic Act No. 10361: Domestic Workers Act (Batas Kasambahay) (The Lawphil Project; accessed 2026-10-25)
- Republic Act No. 11223: Universal Health Care Act (The Lawphil Project; accessed 2026-09-04)
- Republic Act No. 9679: Home Development Mutual Fund Law of 2009 (The Lawphil Project; accessed 2026-09-04)
Last editorial review: 2026-10-25. Sources and regulated claims can change; confirm the current position before acting.
Related Guides

How to hire a yaya in Iloilo City: pay, interviews and the first week
A practical guide to hiring a yaya in Iloilo City, from the Region VI wage floor and interviews to a paid trial and first-week handover.
Singapore Maid Work Permit Renewal: Steps, Fee, and Deadlines
How to renew a migrant domestic worker Work Permit in Singapore: the MOM renewal notice, S$35 fee, security bond, insurance, medical checks, and late renewal.
Domestic Helper Release Letter and Termination in Hong Kong
How Hong Kong families end a domestic helper contract: one month notice, final pay, the 7 day Immigration notice, the release letter, and fill-in templates.